The Brief
- Hymans Robertson Personal Wealth’s UK analysis classifies 49% of working women surveyed as financially vulnerable, compared with 35% of men.
- These are UK findings, not an estimate for Indian women.
- Indian data show progress in financial access alongside continuing differences in earnings and employment.
- A salary’s protective value depends on what remains after commitments, its reliability and access to savings and assets.
- Employers and households need to examine how money and financial risk are shared, alongside improving financial knowledge.
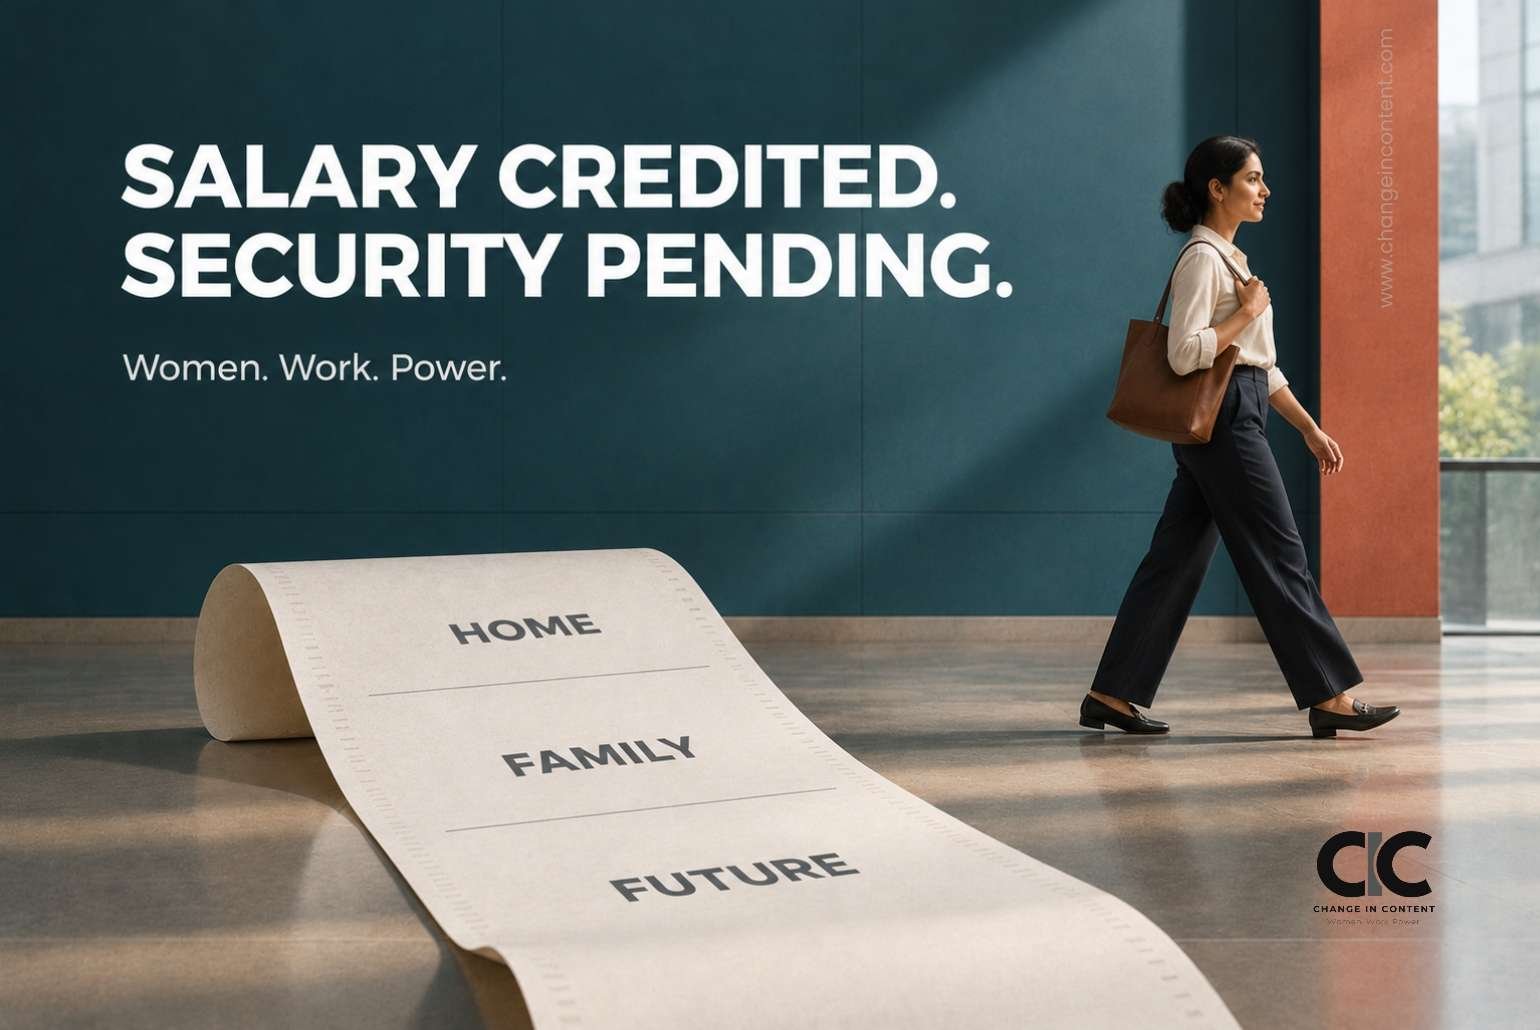
Salary credited. Rent debited. School fees due. A parent’s prescription renewed. By the time anyone asks how she is doing financially, much of the answer has already left her account. Working women and financial vulnerability can belong in the same sentence, even when the salary arrives on time.
We are comfortable celebrating the first pay cheque. The conversation becomes less comfortable when a woman has been earning for years and still cannot absorb an unexpected expense without borrowing or asking someone for help. Employment has changed her life. It may not yet have given her much room to manoeuvre.
October coverage of research by Hymans Robertson Personal Wealth puts 49% of working women surveyed in the UK in its financially vulnerable category, compared with 35% of men. Separately, 42% of women said they often or always felt stressed about their financial situation, against 29% of men.
The firm describes the wider research as a survey of 2,000 UK employees. The full scoring thresholds and gender subgroup sizes could not be verified from the accessible material. The classification should therefore be attributed to the study, rather than treated as a universal diagnosis.
For India, the question is what stands between earning money and feeling protected by it.
The salary has several jobs. Does one of them protect her?
Paying household bills, supporting parents and contributing to a child’s education can be sources of pride. Family support also protects people when individual incomes fail. The problem begins when one person’s future is repeatedly treated as the expense that can wait.
Imagine a couple who divide spending informally. She pays for groceries, school expenses and the small emergencies. He directs more of his income towards long-term assets. The arrangement may be perfectly fair if ownership, access and future benefits are genuinely shared. But unless they discuss those details, the division of bills can hide a division of security.
This is part of the wealth-generation gap for women. Money spent keeping a household running has enormous value, even when it leaves no asset in the spender’s name.
Equal contributions can also produce unequal pressure. Splitting a bill in half takes a larger share of the lower earner’s income. A fair arrangement needs to consider earnings, unpaid responsibilities, existing obligations and what each person can retain for their own future. The appropriate split will differ between households.
The revealing question is what happens if her income stops.
- Can she access the household’s reserves?
- Does she know its debts and insurance arrangements?
- Can she take time to recover from an illness or find another job?
A comfortable family lifestyle does not answer those questions by itself.
India’s progress is real. So is the pressure on the remainder.
The World Bank’s Global Findex 2025 release, based on 2024 data, reports account ownership at roughly 90% for both women and men in India. That is an important foundation for receiving income, making payments and using formal financial services.
The growing presence of women investors in India deserves attention too. Women’s financial lives cannot be reduced to dependence or distress.
Yet an account tells us where money can be held. It cannot tell us how much remains there, whether its owner can use it freely or how long it could cover essential expenses.
Official earnings figures help explain why the remainder deserves scrutiny. India’s PLFS 2025 release puts average monthly earnings in regular wage or salaried work at ₹18,353 for women and ₹24,217 for men. Women’s nominal earnings in this category grew 7.2% from 2024, compared with 5.8% for men. Progress and a substantial gap sit together in the data. These averages cover different jobs and circumstances; they do not measure unequal pay for identical work.
Costs then act on what people have available. India’s provisional September 2026 figures put year-on-year consumer inflation at 5.54%, with food inflation at 7.74%. These are national measures, not the increase in every household’s bills.
For someone with little left after essentials, a rise in those essentials can consume the money intended for savings. A budgeting app can make that shortfall visible. It cannot make the arithmetic disappear.
A job title tells us little about the safety net
Even the word “working” covers very different financial arrangements. In PLFS 2025, regular wage or salaried employment accounted for 18.2% of female workers in usual status, up from 16.6% in 2024. Self-employment accounted for 64.2%.
A salaried employee, a shop owner, a freelance designer and a woman helping in a household enterprise cannot be assumed to have the same payment cycle, benefits or personal access to earnings.
There are costs to remaining employed as well. Travel, childcare, and the price of taking time away from work affect what a job makes possible. When a family weighs whether a woman should continue working, charging the entire childcare bill against her salary makes one career carry the cost of a shared responsibility. The decision also needs to consider future earnings, skills, retirement provision and her own ambitions.
Career opportunities enter the calculation here. A promotion can improve the room available for saving. A role with erratic hours may make dependable childcare harder to arrange. An employer who delays an expense reimbursement effectively asks the employee to finance company business in the meantime.
These are financial wellbeing issues with a workplace address.
The link between equity at work and financial independence becomes practical when we examine those decisions. Access to meaningful work and progression affects a woman’s finances long after a financial-awareness session ends.
Before the money masterclass, inspect the payroll
Financial education can help people understand interest, borrowing, insurance and long-term planning. It becomes patronising when every financial difficulty is treated as a lesson the employee failed to learn.
An employer’s first review should include its own contribution to uncertainty: pay levels, unexplained differences, unpredictable hours, late reimbursements and benefits that employees cannot use easily. A shopping discount is welcome. It should not distract from those questions.
Useful support also needs to fit the immediate problem. Someone facing debt pressure may need confidential, qualified guidance. Someone unable to fund work travel may need an advance rather than a reimbursement next month. A hardship loan may help in a particular case, but it also creates repayments; it cannot be assumed to solve a recurring income shortfall.
Employers should assess financial support without turning private money troubles into performance information. Employees need to know who sees their information, whether an adviser is selling products and what any assistance will cost.
Households have their own review to make. Discuss contributions alongside ownership, access and future provision. If one person reduces paid work for a shared family need, agree how that person’s savings and long-term security will be supported. A vague promise to “take care of everything” leaves too much unclear.
For women themselves, a useful starting point is a clear view of income, essential commitments, debts, accessible savings and benefits. The purpose is to identify where protection is thin. Where income barely covers essentials, that finding should prompt a discussion about resources and responsibilities, rather than another round of self-blame.
Change the Calculation
The UK finding should make us curious about Indian working women’s financial lives, without importing a percentage that was never measured here.
We need to ask better questions than whether a woman earns.
- What does her work allow her to keep?
- What can she decide?
- Who shares the financial consequences when family needs change?
A salary that pays the bills is doing valuable work. A fairer arrangement leaves its earner with something more: the ability to withstand a setback and make a choice.
The pay cheque should help build her future too.
Editorial note and sources
This analysis distinguishes UK survey findings from Indian official data and CIC’s interpretation. The UK results are attributed to Hymans Robertson Personal Wealth as reported by Credit Connect; the producer confirms an overall sample of 2,000 UK employees. Full scoring thresholds, fieldwork dates and gender subgroup sizes were not independently verified. PLFS earnings are group averages, not an equal-pay comparison; Findex measures account ownership rather than personal wealth or control; CPI figures are national year-on-year measures. Household examples are hypothetical. This is general editorial analysis, not individual financial, investment or legal advice.
- Credit Connect: Nearly half of working women feel financially vulnerable
- Hymans Robertson Personal Wealth: Research summary and overall sample
- World Bank: Global Findex 2025 launch findings
- MoSPI: PLFS Annual Report 2025 release
- MoSPI: September 2026 consumer price inflation
