The Brief
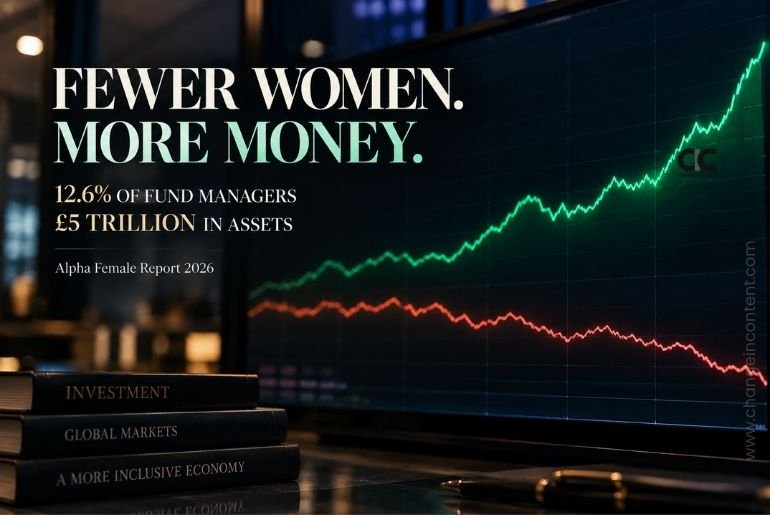
- Women account for 12.6% of active fund managers globally in Citywire’s Alpha Female Report 2026, down from 12.9% last year. Citywire describes it as the first reversal after years of gradual progress.
- The number of active women fund managers fell from 2,371 to 2,283, while Citywire tracks 18,117 managers across 28,649 active funds globally.
- Assets associated with women managers rose sharply, reaching roughly £5 trillion, but most of that money is managed through mixed-gender teams rather than women-only mandates.
- Women are also receiving fewer new opportunities: 83% of new funds launched in 2026 went to a solo male manager or an all-male team, up from 81% last year.
- The report suggests the central problem is no longer whether women can manage significant capital. They demonstrably can. The harder question is whether enough women are entering, remaining and receiving authority in fund management.
Alpha Female Report 2026
5 trillion pounds is an extraordinary amount of money. It is larger than the annual economic output of most countries. And according to Citywire’s Alpha Female Report 2026, that is approximately how much investment capital is now associated with women fund managers and mixed teams that include women.
That might sound like a breakthrough.
Then comes another number. 12.6%. That is women’s share of active fund managers globally. Last year it was 12.9%.
For the first time in the report’s eleven-year history, Citywire has recorded an actual decline in the number of women managing active funds. The Alpha Female Report 2026 is therefore less straightforward than a diversity scorecard.
The money has moved forward. Representation has moved backwards.
88 women disappeared from the count in a year
Citywire counted 2,283 active female fund managers in 2026, compared with 2,371 the previous year. That is 88 fewer women.
The wider active-management industry has also contracted as cheaper passive products continue taking market share. So women are not disappearing from an otherwise expanding profession. But that does not fully explain the gender movement.
In several markets, the population of fund managers declined overall while the number of women fell faster.
Why is that distinction important?
An industry becoming smaller does not inevitably have to become less female.
Citywire now tracks 18,117 portfolio managers running 28,649 active funds worldwide. Women make up just over one in eight of those managers. After years of extremely slow movement upwards, even a 0.3-percentage-point reversal deserves attention.
Not because one year proves a permanent trend. Because progress that moves backwards once reminds us that it was never guaranteed.
We saw a similar warning recently in India, where women’s representation in corporate executive roles fell to 16.7% among companies in the Avtar–Seramount benchmark. Different industry, different dataset, same useful lesson: representation does not automatically keep improving simply because organisations have spent years discussing it.
Then how are women managing more money than ever?
This is where the report becomes considerably more interesting.
Assets managed by women or teams including women increased from roughly £4 trillion to £5 trillion in a year. At first glance, that seems to contradict the representation decline. It does not.
A smaller number of women can manage larger pools of capital.
Markets can rise. Funds can consolidate. Successful managers can receive bigger mandates. And increasingly, large portfolios can be managed by teams rather than a single named fund manager.
Citywire’s data shows that the majority of the increase came through mixed-gender teams.
Assets associated with those teams rose by around £900 billion to approximately £4.3 trillion. By comparison, solo women managers were responsible for around £550 billion, while female-only teams accounted for about £124 billion.
That makes the £5 trillion figure encouraging, but also easy to misread. It tells us women are participating in the management of an enormous amount of capital. It does not tell us women independently control £5 trillion. Those are very different statements.
But the capital figure still destroys one tired assumption
Women are sometimes underrepresented in powerful financial roles as though the disparity itself were evidence of some shortage of capability. The report makes that argument increasingly difficult to sustain.
Citywire finds that the average active woman fund manager is now associated with approximately £2.6 billion, compared with around £2.5 billion for men.
Again, the growth of mixed teams influences that calculation. But even with that caveat, there is no obvious evidence here of women being unable to handle scale.
They are managing billions. They are working across complex markets. And they are taking investment decisions involving enormous sums of client money.
The representation problem therefore looks less like a question of whether women can perform the work and more like a question of how many get the opportunity to keep doing it.
In finance, that’s crucial because authority is unusually measurable.
A fund manager does not simply hold a title. There is capital attached to the role. Performance can be tracked. Mandates can be won and lost.
If women entrusted with billions can remain only 12.6% of the profession, capability cannot be the entire explanation.
The new-fund number may be more revealing than the headline
For us, one of the strongest findings in the Alpha Female Report 2026 sits away from the 12.6% figure.
Among funds newly launched during 2026, 83% were handed either to an individual male manager or an all-male management team. Last year, that figure was 81%. That is a pipeline number.
Existing female managers can accumulate assets and become increasingly successful while relatively few women receive the next generation of mandates. Both things can happen at the same time.
Imagine a company with five very senior women whose responsibilities keep expanding. It might look increasingly powerful from the outside. But if almost every new leadership appointment goes to men, its future becomes less diverse even while its existing women become more influential.
Fund management appears to be showing a version of that tension.
The women who have broken through may be trusted with enormous responsibility. The door behind them is not necessarily opening at the same speed.
Active ETFs are not starting from a better place
This becomes particularly significant when looking at newer investment products.
Women account for only 10.3% of active ETF managers, according to the 2026 data. That is down from 10.9% the previous year. It deserves attention because newer parts of an industry sometimes provide opportunities to escape older talent structures.
Here, the emerging segment appears to be reproducing a familiar imbalance.
If newer products begin with heavily male manager populations, correcting the gap later becomes harder. Talent pipelines become established. Track records accumulate. Successful managers receive larger mandates.
Future appointments are made from the people who already possess those track records. Representation therefore compounds much as capital does. Early opportunity matters.
Women also appear to spend less time holding mandates
Citywire reports an average tenure of 4.6 years for women fund managers, compared with 5.9 years for men. Across managers who held funds at some point during the previous decade, 46% of women were no longer managing those funds by 2026, compared with 30% of men.
That does not mean all those women left the profession. Managers can move funds, firms or responsibilities.
Citywire’s own previous work has warned against interpreting every fund departure as a career exit. But the persistent difference still asks a useful question: What happens after women enter fund management?
Citywire explored that question separately in 2025 by interviewing six former female portfolio managers. Their circumstances differed, but recurring issues included the intensity of an “always on” profession, parenthood, presenteeism, fewer workable paths back after stepping away, and the value of team-based fund management.
There is no evidence that one factor explains the 2026 decline. Nor should childcare become the automatic explanation whenever women leave an industry.
The more useful point is that retention belongs beside recruitment when assessing representation.
Mixed teams may be part of the opportunity
One of the more encouraging developments is the growth of mixed-gender management teams.
A decade ago, Citywire reported that such teams represented 6.7% of manager teams. By 2025, that figure had reached 14.9%. There are practical reasons this model can matter.
- Portfolio management involves continuous responsibility.
- Markets do not pause for maternity leave.
- A major geopolitical event cannot be rescheduled because one manager is unavailable.
- Teams can distribute coverage, institutional knowledge and decision-making in ways that make extended absence less career-threatening for everybody.
That does not make team structures a women’s policy. Quite the opposite. A resilient investment team should be able to survive any member being temporarily unavailable.
The danger is different. Women can become highly visible members of mixed teams while still being less likely to hold the lead mandate, receive equivalent remuneration or be recognised as the primary decision-maker.
The Alpha Female figures do not tell us whether that is systematically happening. But the huge difference between assets managed through mixed teams and assets held by solo women makes authority within the team a useful next question.
Geography shows that 12.6% is not inevitable
Female representation varies dramatically by market.
Taiwan leads the Citywire country table at 31.1%, followed by Singapore at 24.8% and Hong Kong at roughly 24%.
Europe is considerably more uneven. Spain stands at 21.1% and Italy at 19.4%, while Switzerland has 8% female representation and Germany 7.2%.
Those differences are useful because they challenge any explanation based purely on the nature of fund management itself.
The job is demanding everywhere. Markets are volatile everywhere. Performance pressure exists everywhere. Yet some markets produce substantially more women managers than others.
That suggests talent structures, recruitment, professional networks, workplace cultures and career pipelines can make a difference. There is nothing intrinsic about 12.6%.
The bigger question is who controls capital
Women and finance are often discussed through the consumer side.
- Do women invest?
- Do they save?
- Do they understand markets?
- Are financial products designed for them?
Those questions matter. But there is another side of the financial system that deserves equal attention: Who decides where everybody else’s money goes?
Fund managers influence where pension savings, investment accounts and institutional assets are allocated.
- They decide which companies deserve capital.
- Which sectors offer opportunity.
- Which risks are acceptable.
- Which management teams they trust.
This is economic power in a very direct form. That is why the gender composition of asset management matters beyond workplace diversity. It concerns participation in one of the systems through which capital itself is distributed.
Our earlier conversation with Juzer Tambawalla on women and inclusion in BFSI examined how financial services have opened significantly to women while some senior and specialised roles remain much less balanced. Fund management provides a particularly sharp example because both representation and the capital attached to responsibility can be measured.
We should not read one decline as a decade erased
There is a temptation with reports like this to declare that progress has failed. That would be too easy. When Citywire began the Alpha Female series in 2016, women represented about 10.3% of the global fund-manager population.
By 2025, they had reached 12.9%. That is progress. Slow progress, but progress.
The 2026 fall to 12.6% does not erase it. What it does erase is the comforting assumption that the line will always move in the same direction. That is useful.
We recently wrote about women losing ground in leadership globally because a similar pattern is beginning to appear across different corporate datasets: representation gains can stall or reverse even after years of diversity initiatives.
The lesson from fund management is not that women need another campaign telling them finance is open to them.
The numbers suggest something more specific. The industry needs to understand:
- who receives the first mandate
- who receives the second
- whose fund grows
- who becomes lead manager
- who remains after five years
- and who gets the next £5 billion to manage.
Change in Perspective: More Money is Good. More Women Still Matters.
The £5 trillion number deserves celebrating.
Women are helping manage capital at a scale that makes any lingering doubt about their place in fund management increasingly absurd. But capital concentration among successful women cannot substitute for representation.
A profession could theoretically have fewer and fewer women while the remaining women manage more and more money. That would demonstrate extraordinary success among those who stayed. It would not demonstrate equal access to the profession.
The Alpha Female Report 2026 therefore gives us two measures of progress.
- One asks: How much responsibility do women have once they get there? On that measure, the numbers look encouraging.
- The second asks: How many women get there, receive mandates and remain? On that measure, 2026 moved backwards.
Both matter. Because eventually a genuinely inclusive asset-management industry should not force us to choose between women having more power and more women having power. It should be capable of producing both.
Editorial Note & Sources
The Alpha Female Report measures representation among active fund managers in Citywire’s global database. Asset figures associated with women include capital managed by mixed-gender teams, and should therefore not be interpreted as assets solely or independently controlled by women. A year-on-year fall from 12.9% to 12.6% establishes a reversal in the 2026 dataset, not proof of a permanent long-term decline. Change in Content’s interpretation focuses on representation, mandates, retention and authority rather than assuming a single cause for the change.
Sources
- Citywire: Alpha Female Report 2026/“Alpha Female 2026: Progress for women fund managers goes into reverse”, 14 September 2026. Primary source for Citywire’s finding that women account for 12.6% of active fund managers globally and for the report’s overall conclusions.
- Citywire: Alpha Female Report 2026 country reporting. Citywire’s regional reporting accompanying the global report, including the different trajectories across markets.
- Citywire: “Why women leave fund management”, September 2025. Citywire’s qualitative investigation with former women portfolio managers, used only to provide background on retention, working culture, parenthood, teams and career continuity rather than to explain the 2026 decline causally.
- Citywire: Fund groups ranked by gender diversity. Supporting Citywire data based on the Alpha Female dataset, showing representation across global asset-management groups.